How to File an Insurance Claim for Metal Roof Hail Damage
Finding out your beautiful, durable metal roof has suffered hail damage can feel like a punch to the gut. You invested in a metal roof for its longevity and resilience, so when a hailstorm hits and leaves its mark, it's natural to feel confused, frustrated, and unsure of what to do next. This comprehensive guide is here to walk you through the often-stressful process of filing an insurance claim for metal roof hail damage, helping you understand what to look for, how to document it, and how to navigate the insurance process with confidence.
Understanding Hail Damage on Metal Roofs
When that hailstorm finally passes, and you step outside to assess the damage, your metal roof might look perfectly fine from a distance. But don't let its tough exterior fool you; hail can inflict significant, often subtle, damage that compromises your roof's integrity and lifespan. It’s crucial to know what you’re looking for and how metal responds differently than, say, traditional asphalt shingles.
What Hail Damage Looks Like on Metal Beyond the Obvious
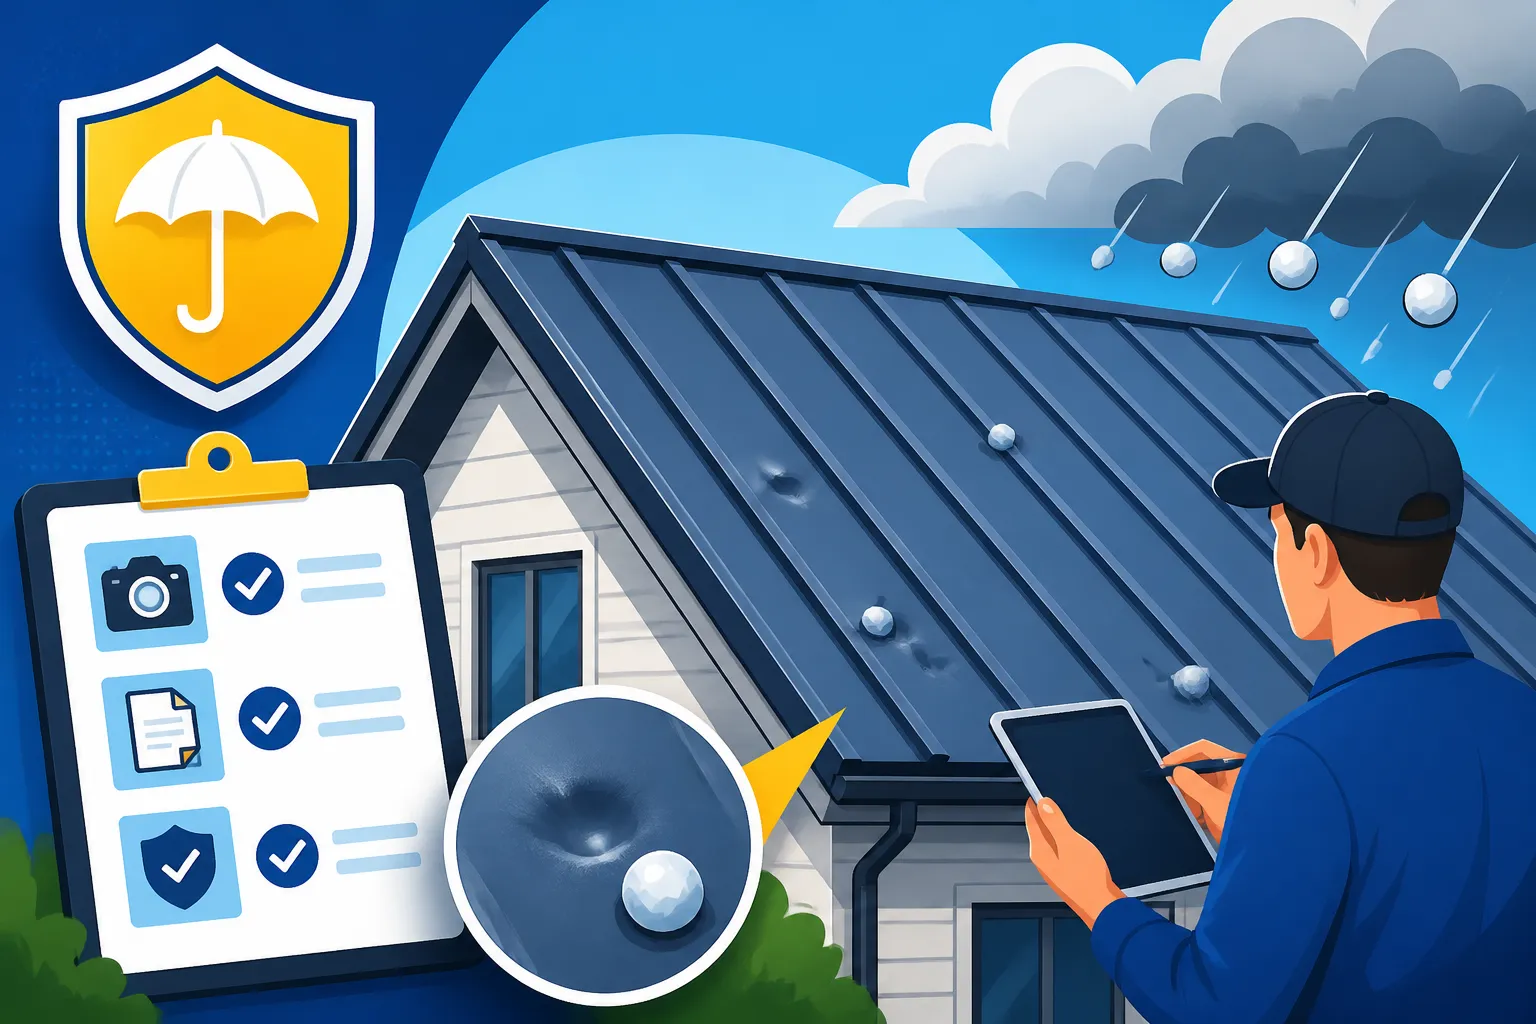
Unlike asphalt shingles, where hail can shatter granules or create visible divots, metal roof hail damage isn't always as apparent. Sure, large hailstones can leave obvious dents, sometimes even deep enough to penetrate the protective coating or material itself, leading to immediate concerns. But often, the damage is far more insidious.
For instance, you might see small, shallow dimples or pockmarks across the panels. These might seem merely cosmetic at first glance, but even minor impacts can compromise the protective paint finish. This outer layer, typically a Kynar 500 or SMP coating, is vital for UV protection, color retention, and preventing corrosion. Once this coating is breached, even slightly, the underlying metal is exposed to the elements, making it vulnerable to rust, fading, and accelerated deterioration over time. Think of it like a scratch on your car; a tiny scratch can lead to a big rust spot if not addressed. For metal roofs with granules, like stone-coated steel, hail can strip away these protective granules, similar to asphalt shingles, exposing the steel substrate beneath. Furthermore, hail can impact the fasteners, causing them to loosen or the sealant around them to crack, creating potential entry points for moisture. It’s not always about a big hole; sometimes it's a slow, creeping issue.
Why Metal Roofs React Differently to Hail
Metal roofs are renowned for their durability, often carrying a Class 4 impact resistance rating, the highest available. This means they are significantly more resistant to severe weather events compared to their asphalt counterparts. However, "resistant" doesn't mean "impervious." While a metal roof might not shed granules or tear like an asphalt shingle roof, it has its own unique vulnerabilities to hail.
Asphalt shingles are designed to absorb some impact, and damage usually manifests as granule loss, bruising, or cracks. For a metal roof, the impact energy is transferred through the panel, often resulting in dents or dings. The severity depends on several factors: the size and density of the hailstones, the angle of impact, the gauge (thickness) of the metal, and the type of metal itself. For instance, a 29 gauge metal roof will likely show more visible denting than a thicker 24 gauge metal roof. Aluminum, being a softer metal, might dent more readily than steel or zinc, but it won't rust. Steel, while strong, can be more susceptible to surface coating damage that leads to rust if left untreated. This distinct reaction to hail is why insurance adjusters need specific expertise when assessing metal roof damage, and why what constitutes a "damaged" metal roof can differ significantly from other roofing materials. Understanding the differences in materials is also key to evaluating the overall Metal Roof Cost: Complete 2026 Guide.
The Immediate Aftermath: What to Do and Not Do
When a major hailstorm rolls through, the natural instinct is often to rush outside, look up, and try to figure out what just happened. While prompt action is good, it’s important to prioritize safety and follow a systematic approach to ensure you protect yourself and your potential insurance claim.
Prioritizing Safety and Documentation
First and foremost, safety is paramount. Do not climb onto your roof immediately after a storm, especially if there's standing water, debris, or compromised structural integrity. The roof could be slick, unstable, or you might not be equipped to safely assess the damage. If you believe there’s active leaking, focus on mitigating interior damage with buckets and tarps, if safe to do so.
Once safe to observe from the ground, start documenting everything. Take clear photos and videos of your roof from various angles around your property. Zoom in on any visible dents, scrapes, or areas where the coating appears compromised. Don't forget to document other areas of your property that may have been hit, like gutters, siding, windows, or even your car – this helps establish the severity of the storm in your area. Make a note of the date and time of the storm, the approximate size of the hailstones (compare them to common objects like quarters or golf balls), and the direction the storm came from. Talk to neighbors; if their roofs are clearly damaged, it further supports your claim. This initial documentation is crucial evidence for your insurance company. Remember, the more comprehensive your initial records, the smoother your claim process is likely to be.
Contacting Your Insurance Provider
As soon as it's safe and you've completed initial documentation, contact your insurance provider immediately. Most policies require prompt notification of damage. The sooner you report it, the better. Delaying can sometimes complicate the process or even lead to issues with coverage, as insurers might argue the damage occurred at a later date.
When you call, be prepared with your policy number, the date of loss, and a brief description of the damage you've observed. This is also a good time to review your policy documents. Pay close attention to your deductible amount, and any specific endorsements or exclusions related to roof damage. Crucially, look for a "cosmetic damage exclusion." This is a common clause in some policies, especially for metal roofs, that might limit or exclude coverage for damage that doesn't affect the roof's functional integrity. Knowing this upfront will help you understand what your policy covers and what challenges you might face. Many homeowners seek to understand their potential Metal Roof Insurance Savings & Discounts when first installing their roof, but it's equally important to know the limitations during a claim.
Finally, be wary of "storm chasers" – contractors who go door-to-door immediately after a storm, pushing for quick repairs or offering to handle your insurance claim for you. While some contractors are legitimate, others are not. Always vet any contractor thoroughly before signing anything. You want a trusted professional, not someone who disappears after the storm passes.
Navigating the Insurance Claim Process
Once you've reported the damage, the wheels of the insurance claim process start turning. This stage can feel overwhelming with inspections, paperwork, and decisions, but being prepared and proactive can make a significant difference.
Scheduling the Inspection and Being Prepared
Your insurance company will assign an adjuster to assess the damage to your roof. This person's job is to evaluate the extent of the damage, determine if it's covered under your policy, and estimate the cost of repair or replacement. When scheduling the inspection, try to be present. This allows you to point out any areas of concern you’ve noted and ask questions.
Before the adjuster arrives, ensure your documentation (photos, videos, storm dates, hail size notes) is easily accessible. If you've had a qualified roofing contractor conduct an initial assessment, have their report ready as well. It's often beneficial to have a reputable roofing contractor present during the adjuster's inspection. A knowledgeable contractor can speak the technical language of roofing, ensure all damage is identified, and discuss repair options and costs directly with the adjuster. They can also explain why seemingly minor dents might have long-term implications for your roof's protective coatings and structural integrity. Learning how to read and compare metal roof quotes will be invaluable here, as you'll want to ensure the contractor's assessment aligns with potential repair or replacement costs.
Understanding Your Claim Options and Settlement
After the inspection, the adjuster will provide their assessment and, if approved, an initial settlement offer. It’s vital to understand the difference between Actual Cash Value (ACV) and Replacement Cost Value (RCV) policies.
- Actual Cash Value (ACV): This pays for the depreciated value of your roof. For example, if your metal roof has a 50-year lifespan and is 10 years old, the insurance company might only pay 80% of the replacement cost, factoring in that depreciation. This means you'll be responsible for the difference.
- Replacement Cost Value (RCV): This policy typically pays the full cost to repair or replace your roof with new materials of similar kind and quality, without deduction for depreciation. You usually receive an initial payment for the ACV, and then the recoverable depreciation is paid out once the repairs or replacement are completed and you provide proof of payment to the contractor.
Always clarify which type of coverage you have. If the initial settlement offer seems low or doesn't cover the full extent of the damage, don't be afraid to challenge it. You can present your contractor's detailed estimate and any additional evidence. Sometimes, a negotiation or a second review can lead to a more favorable outcome. In complex cases, especially if you feel the insurance company is being unreasonable, you might consider consulting a public adjuster, who works for you (not the insurance company) to negotiate the claim. However, public adjusters take a percentage of the settlement, so weigh this option carefully.
Working with Contractors Post-Claim Approval
Once your claim is approved and you understand your settlement, the next step is hiring a reputable contractor to perform the repairs or replacement. This is a critical stage. Start by getting multiple detailed bids from local, experienced metal roofing contractors. These bids should itemize materials, labor, and any other associated costs like permit fees or tear-off of old materials. Be sure the bids align with the scope of work approved by your insurance company. You can find more details on how to hire a metal roofing contractor in our extensive guide.
Verify that the contractor is licensed, bonded, and insured. Ask for references and check their recent work. Ensure they have specific experience with metal roofing and understand the nuances of working on insurance claims, as this often involves specific documentation and communication requirements. A contractor who specializes in metal roofs will also be better equipped to handle any unexpected issues that might arise. Don't simply go with the lowest bid; prioritize quality workmanship and reliability, as your roof is a long-term investment.
Common Challenges and Solutions in Hail Damage Claims
Even with careful preparation, filing an insurance claim for metal roof hail damage can present unique obstacles. Understanding these challenges beforehand can help you navigate them more effectively.
The "Cosmetic Damage Exclusion" Dilemma
One of the most frequent hurdles homeowners with metal roofs face is the "cosmetic damage exclusion" in their insurance policy. This clause is becoming increasingly common, especially in hail-prone regions like Texas, Colorado, and Oklahoma. Essentially, it states that if hail damage is purely aesthetic—meaning it doesn't affect the roof's ability to protect your home or its functional lifespan—the insurance company may not cover the cost of repairs or replacement.
For metal roofs, this is particularly tricky. A dent might not cause a leak right away, but if it compromises the protective coating, it significantly increases the risk of premature rust and degradation, thus affecting the roof's long-term functional integrity. The challenge is convincing your insurer that seemingly minor dents are not merely cosmetic but lead to a functional impairment over time. It’s crucial to present arguments that emphasize the impact on the coating, potential for rust, and reduced lifespan. Documenting specific panel types can also help, as some, like a standing seam metal roof, rely heavily on their factory finish for longevity. This is an area where a knowledgeable contractor's assessment can be invaluable in articulating the functional impact of the damage to the adjuster. For more on this, check out our guide on what is the cosmetic damage exclusion on metal roofs.
Dealing with Underpayments or Denials
It's disheartening to receive an underpayment or, worse, a denial of your claim, especially when you know your roof is genuinely damaged. However, it's not always the final word.
If your claim is underpaid, meaning the settlement amount isn't enough to cover the necessary repairs, gather additional evidence. Get detailed estimates from multiple reputable contractors that clearly show the disparity. Ask your contractor to provide a report explaining why their costs are higher and why certain repairs are essential for restoring your roof to its pre-loss condition. Present this information to your adjuster and request a re-evaluation. Sometimes, an experienced roofing professional can highlight factors the adjuster might have overlooked, such as the need for specialized materials, specific installation techniques, or the actual cost of a Standing Seam Metal Roof Cost.
If your claim is denied, ask for the denial in writing, clearly stating the reasons. Review your policy again to understand the basis for their decision. If you believe the denial is unfounded, you have several avenues:
- Appeal: Most insurance companies have an appeal process. Submit a written appeal with all your supporting documentation, including contractor reports, photos, and any relevant sections of your policy that support your claim.
- State Department of Insurance: You can file a complaint with your state's Department of Insurance. They act as a regulatory body and can sometimes mediate disputes between policyholders and insurers.
- Legal Consultation: As a last resort, if you've exhausted all other options and believe you have a strong case, you might consider consulting with an attorney specializing in insurance claims. They can advise you on your legal rights and options.
Remember, the goal is to get your metal roof repaired or replaced to its original quality. Persistence, detailed documentation, and expert support are your best tools.
Hail Damage Claim Assessment for Metal Roofs vs. Asphalt Shingles
Understanding how different roofing materials are assessed for hail damage can help set realistic expectations for your insurance claim.
| Feature | Metal Roof Hail Damage | Asphalt Shingle Hail Damage | Insurance Viewpoint (General) |
|---|---|---|---|
| Visible Impact | Dents, dings, pockmarks, scraped or cracked paint/coating, fastener damage. May be subtle. | Granule loss, bruising (soft spots), cracks, fractures, mat exposure. Often more obvious. | Metal often faces "cosmetic exclusion" unless functional integrity is clearly compromised (e.g., coating breach leading to rust potential). Shingles are typically functional damage. |
| Primary Concern | Compromised protective coatings (leads to rust/fading), reduced lifespan, potential leaks from fasteners. | Loss of protective granules, reduced UV protection, accelerated aging, direct water infiltration. | Functional damage is generally covered; cosmetic damage may not be, depending on policy. Argument focuses on whether coating damage is functional. |
| Repair vs. Replace | Often requires panel replacement for severe dents or widespread coating damage. Patching can be difficult to match. | Spot repairs for minor granule loss, but often full replacement for widespread damage. | Metal repairs can be more complex/costly per area; matching existing patina/color is hard. Shingle replacement is more standardized. |
| Inspection Focus | Looking for dents, coating delamination, fastener integrity, evidence of underlying metal exposure. | Examining granule density, bruising, crack patterns, gutter damage. | Adjusters need specific expertise for metal roofs to identify non-obvious functional damage. |
| Impact on Lifespan | Coating damage drastically reduces expected lifespan, even if not immediately leaking. | Granule loss immediately reduces UV protection and roof lifespan. | Functional impairment from reduced lifespan is a key argument for metal roof claims. |
Final Considerations for Your Metal Roof Claim
Navigating a metal roof hail damage claim can be intricate, but being informed and prepared puts you in the best position. Ensure you have clear, comprehensive documentation, thoroughly understand your insurance policy, and partner with a reputable metal roofing contractor who can accurately assess the damage and articulate its functional impact to your insurer.
Remember to leverage resources like our guide on Metal Roof Repair vs Replacement: How to Decide if the damage seems extensive. Don't hesitate to ask questions, challenge assessments you believe are incorrect, and advocate for the proper repair or replacement your durable metal roof deserves. After all, you invested in a metal roof for its long-term benefits, and getting fair compensation for hail damage helps protect that investment for years to come.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.